
Financing a new Silverado 1500 comes down to four numbers: the price you negotiate, your down payment, your interest rate, and your loan term. Get those right, and the monthly payment takes care of itself. Here is how each one works, what lenders look at, and how to avoid the mistakes that cost Chicagoland truck buyers the most.
What Determines Your Silverado 1500 Monthly Payment?
Four factors set your payment: the vehicle price, your down payment or trade-in equity, your APR, and your loan length. A longer term lowers the monthly figure but raises total interest, so an 84-month loan can look affordable while costing thousands more overall. Always ask for the total cost of borrowing, not just the monthly number.
Start with the Trim, Not the Payment
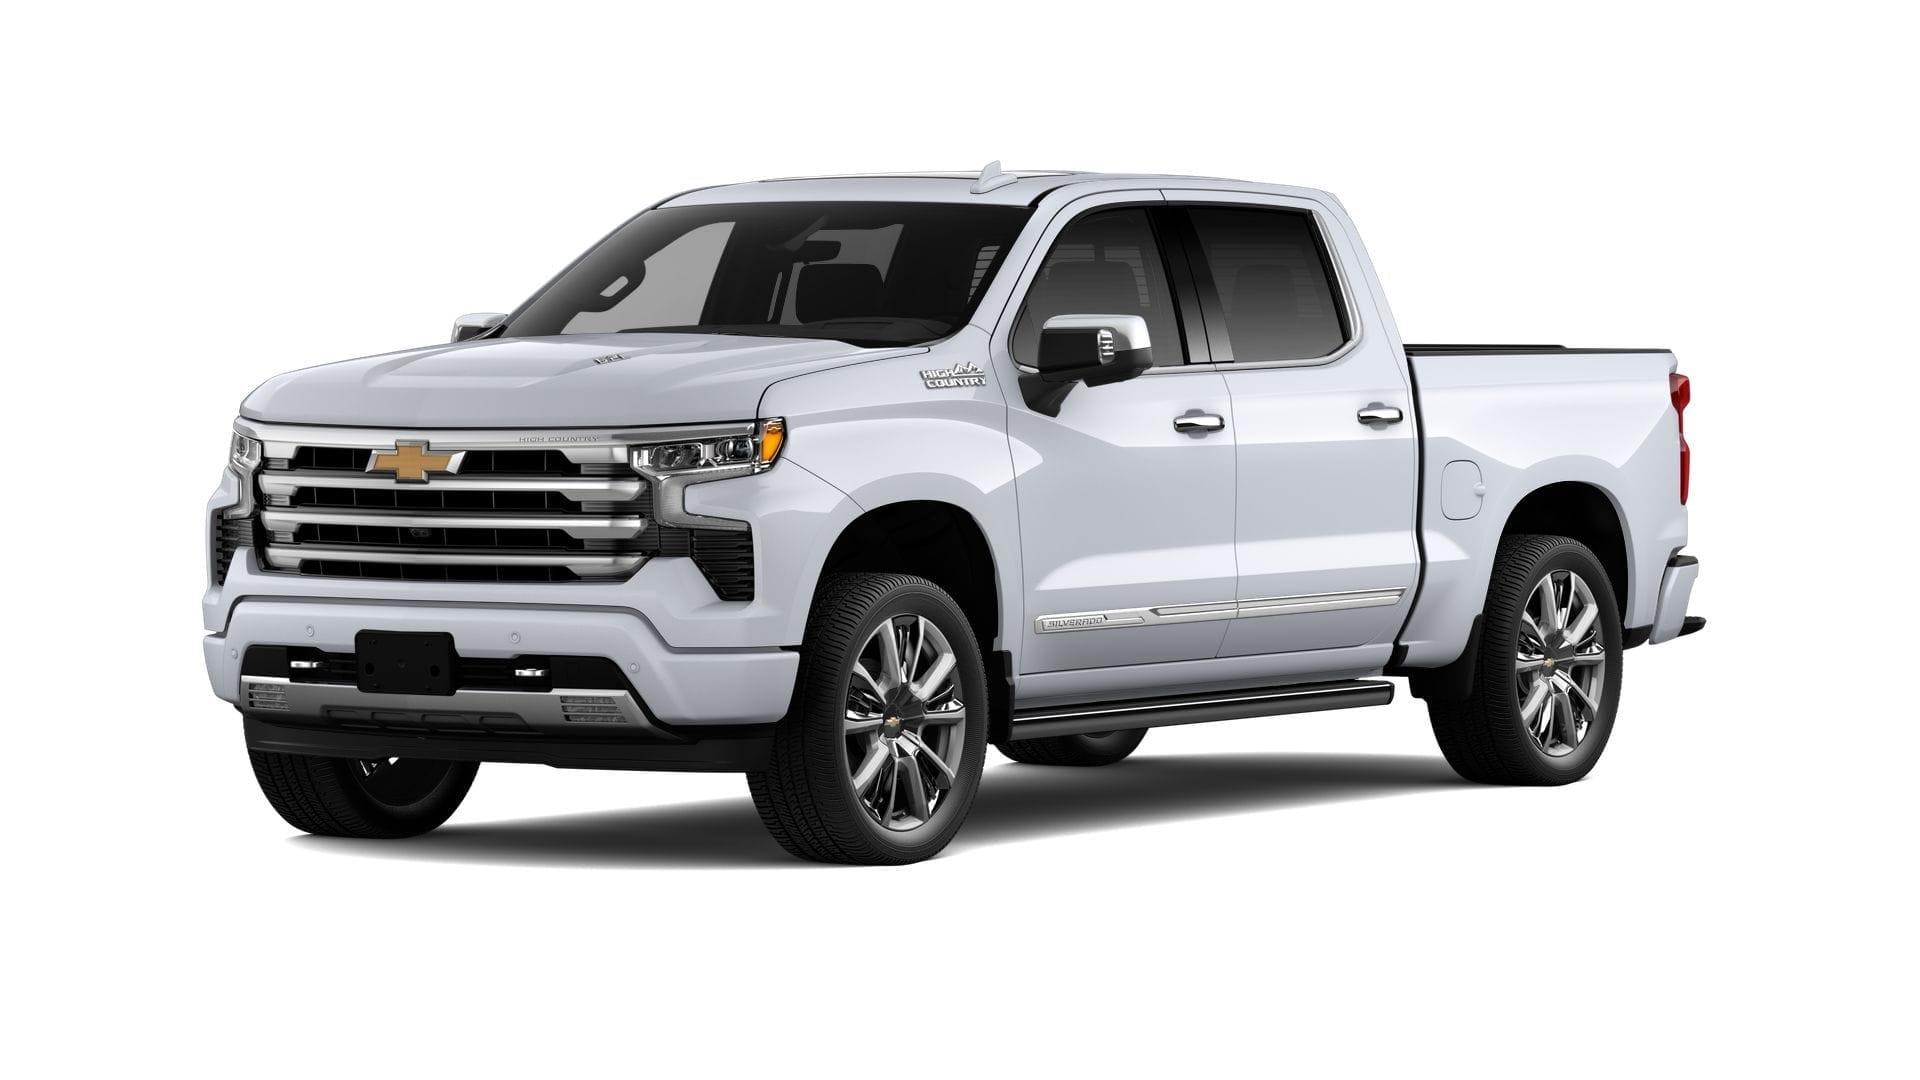
The Silverado 1500 ranges from work-ready trims to well-equipped models with available diesel power, and the price gap between them is significant. Decide what you need before you talk numbers. A contractor in Joliet hauling equipment every day has different needs than a commuter on I-80 who tows a boat a few weekends a year. Financing a trim, you will actually use features that stretch for features you will never touch.
What Credit Score Do You Need?
There is no single cutoff. Lenders weigh your credit history, income, existing debt, and down payment together, and higher scores generally earn lower rates. Before you shop, review your credit reports for errors. Multiple auto loan applications within a short window are typically treated as one inquiry for scoring purposes, so comparing offers should not hurt you. If your credit is still building, a larger down payment or a co-signer can improve your options.
How Much Should You Put Down?
A common guideline is 10 to 20 percent of the purchase price. A bigger down payment reduces the amount you finance, cuts the interest you pay, and helps you avoid owing more than the truck is worth early in the loan. Your trade-in counts too. Positive equity in your current vehicle can cover part or all of your down payment.
Financing vs. Leasing a Silverado
Financing builds ownership and comes with no mileage limits. Leasing typically lowers the monthly payment but caps annual miles and adds wear charges. If you commute from Orland Park to the Loop or run job sites from Tinley Park to Mokena, miles add up quickly, and financing usually fits high-mileage, work-use drivers better.
Chicagoland Costs to Budget Beyond the Loan
Your payment is not your full cost of ownership. Illinois winters mean road salt, so plan for regular washes and underbody care. Get an insurance quote for a full-size truck before you sign. Add registration, taxes, and fuel for stop-and-go commutes on I-57 and Harlem Avenue. If you are financing with little down, ask about GAP coverage.
Five Steps to a Smoother Approval
1. Check your credit reports and correct any errors.
2. Set a budget based on total cost, not only the monthly payment.
3. Get pre-approved so you know your range before you shop.
4. Have your trade-in appraised.
5. Compare the final out-the-door price and APR, not just the payment.
Ready to Finance Your Silverado 1500?
Skip the guesswork and talk with the team at Phillips Chevrolet in Frankfort. We will walk you through trims, trade-in value, and financing options in plain language, with no pressure. Browse our Silverado 1500 inventory online, then stop by or call to start your credit application. Your new truck is closer than you think.
When you visit Phillips Chevrolet, with locations in Frankfort, Lansing, and Bradley, you’re visiting the best in the business. Family-owned and operated for over 50 years, we don't just sell cars; we build relationships. Our commitment to excellence has earned us the title of Cars.com 'Chevrolet Dealer of the Year, ' ranking #1 in the United States among over 3,000 Chevy dealerships, and recognition as the #1 Selling Chevy Dealer in Illinois for 20 years in a row. We are also a JD Power 'Dealer of Excellence' and proudly maintain an A+ Rating with the Better Business Bureau. With Illinois’ largest Chevrolet inventory and a team dedicated to award-winning service, we’re ready to help you find your next dream car.
FAQ: Financing a New Chevrolet Silverado 1500
Q: What is a good loan term for a new Silverado 1500?
A: Shorter terms cost less in interest, but many buyers choose 60 to 72 months to keep payments manageable. Choose the shortest term your budget comfortably supports.
Q: Can I finance a Silverado with less than perfect credit?
A: Often, yes. Approval and rate depend on your full financial profile, and a larger down payment can help. Talk with a finance team about your options before assuming you will be turned down.
Q: Should I get pre-approved before visiting the dealership?
A: It is a smart move. Pre-approval shows your budget range and gives you a rate to compare against any dealership offer.
Q: Does my trade-in lower my monthly payment?
A: Yes. Trade-in value reduces the amount you finance, which lowers your payment and total interest.
Q: Is it better to lease or finance a truck in the Chicago area?
A: If you drive high mileage, tow, or use the truck for work, financing usually makes more sense. Leasing suits drivers who stay within mileage limits and prefer a new truck every few years.